In some business sales, projections are relatively straightforward. There is consistent historical cash flow, stable margins, and enough operating history that buyers and lenders can reasonably extend what already exists. The past provides a solid foundation, and the future doesn’t require much interpretation.
In other deals, that foundation has shifted. The business may have added a new product line, changed its distribution model, adjusted pricing, or reorganized operations. Recent performance may not fully reflect long-term potential, but it also can’t be ignored. When the business has evolved, historical results alone no longer explain the future — and projections require clear, plausible assumptions to bridge that gap.
This is where sellers play a critical role. A well-prepared seller can materially improve the likelihood of a deal closing by helping the buyer articulate reasonable assumptions. That doesn’t mean selling a story. It means providing operational context, historical data, and evidence that explains what has changed, what is working, and what is realistically achievable.
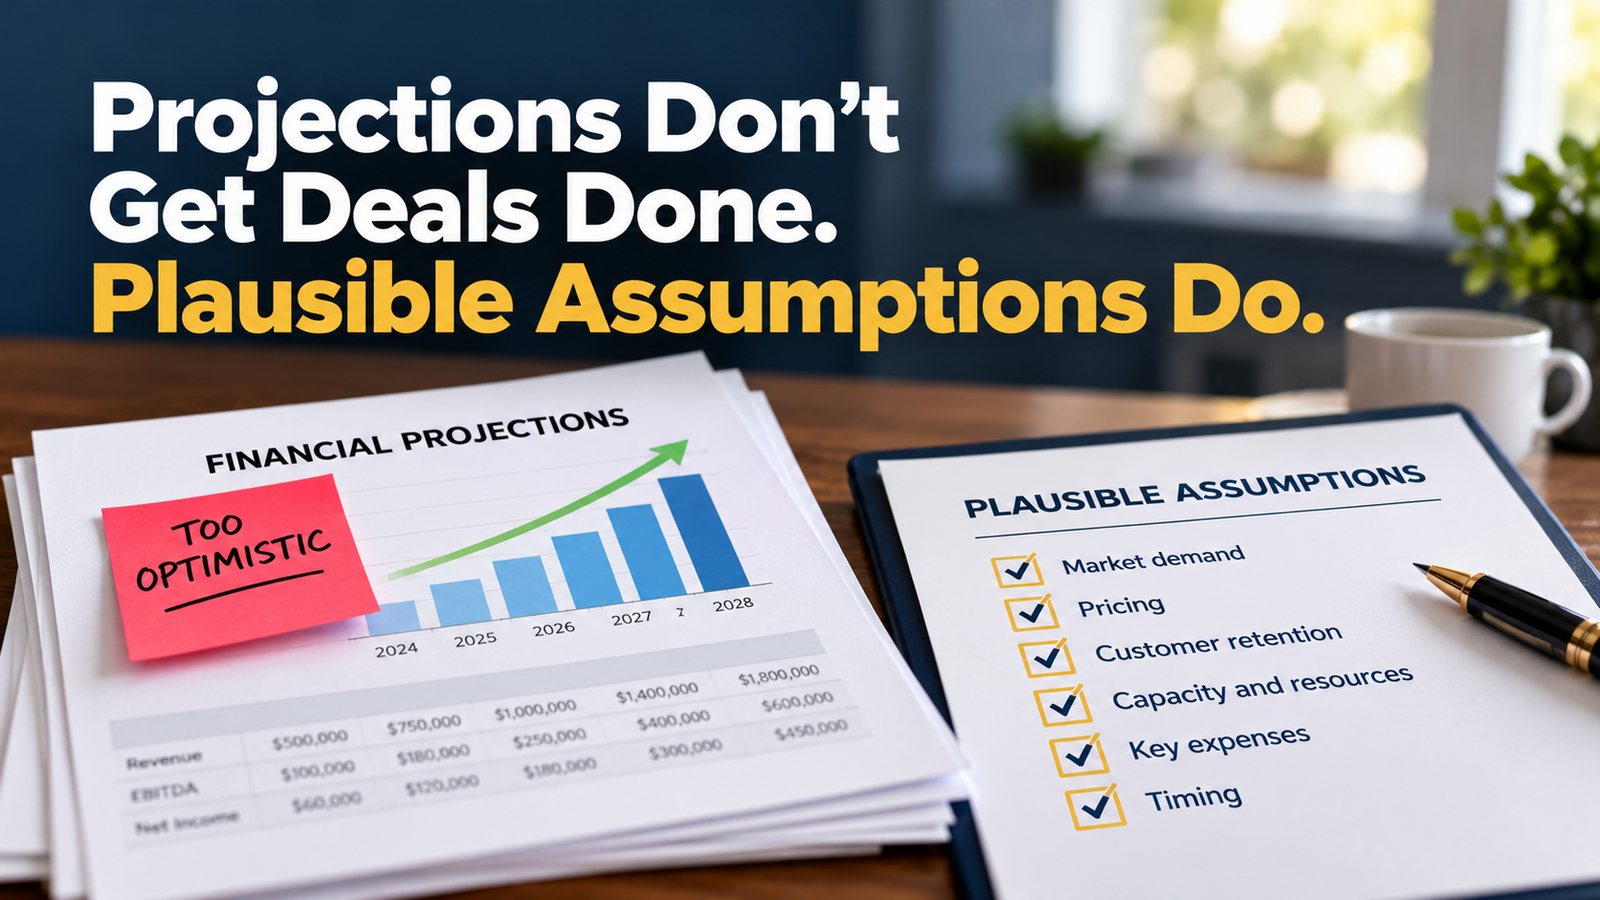
When lenders review projections, they aren’t focused on whether the numbers look attractive. They’re asking what has to occur operationally for those numbers to happen — and whether those changes are realistic. If revenue is expected to grow, what specifically drives that growth? Increased capacity, new channels, additional marketing, pricing adjustments? If expenses are projected to decline, what exactly is changing to make that possible?
Deals lose credibility when growth appears on paper but nothing in the operation changes to support it. Revenue rises while staffing, capacity, or spend remain flat? Margins improve without any identified efficiencies? When the math and the operations don’t align, lenders see execution risk, not upside.
The same applies to people-based assumptions. “A better owner will run this more effectively” is not a bankable thesis. Motivation doesn’t create systems, reduce dependency, or stabilize cash flow. Lenders underwrite repeatability, not optimism.
At its core, acquisition lending is about execution risk. Deals feel safer when projections resemble a continuation of what already works, particularly in the first year. Conservative assumptions signal understanding and discipline, not lack of confidence.
Projections don’t get deals approved. Plausible, justifiable assumptions do. When the operational logic makes sense, the numbers become credible. When it doesn’t, no enthusiasm can fix it.
What are businesses in your industry selling for? Request a complimentary Industry Multiples Insight.