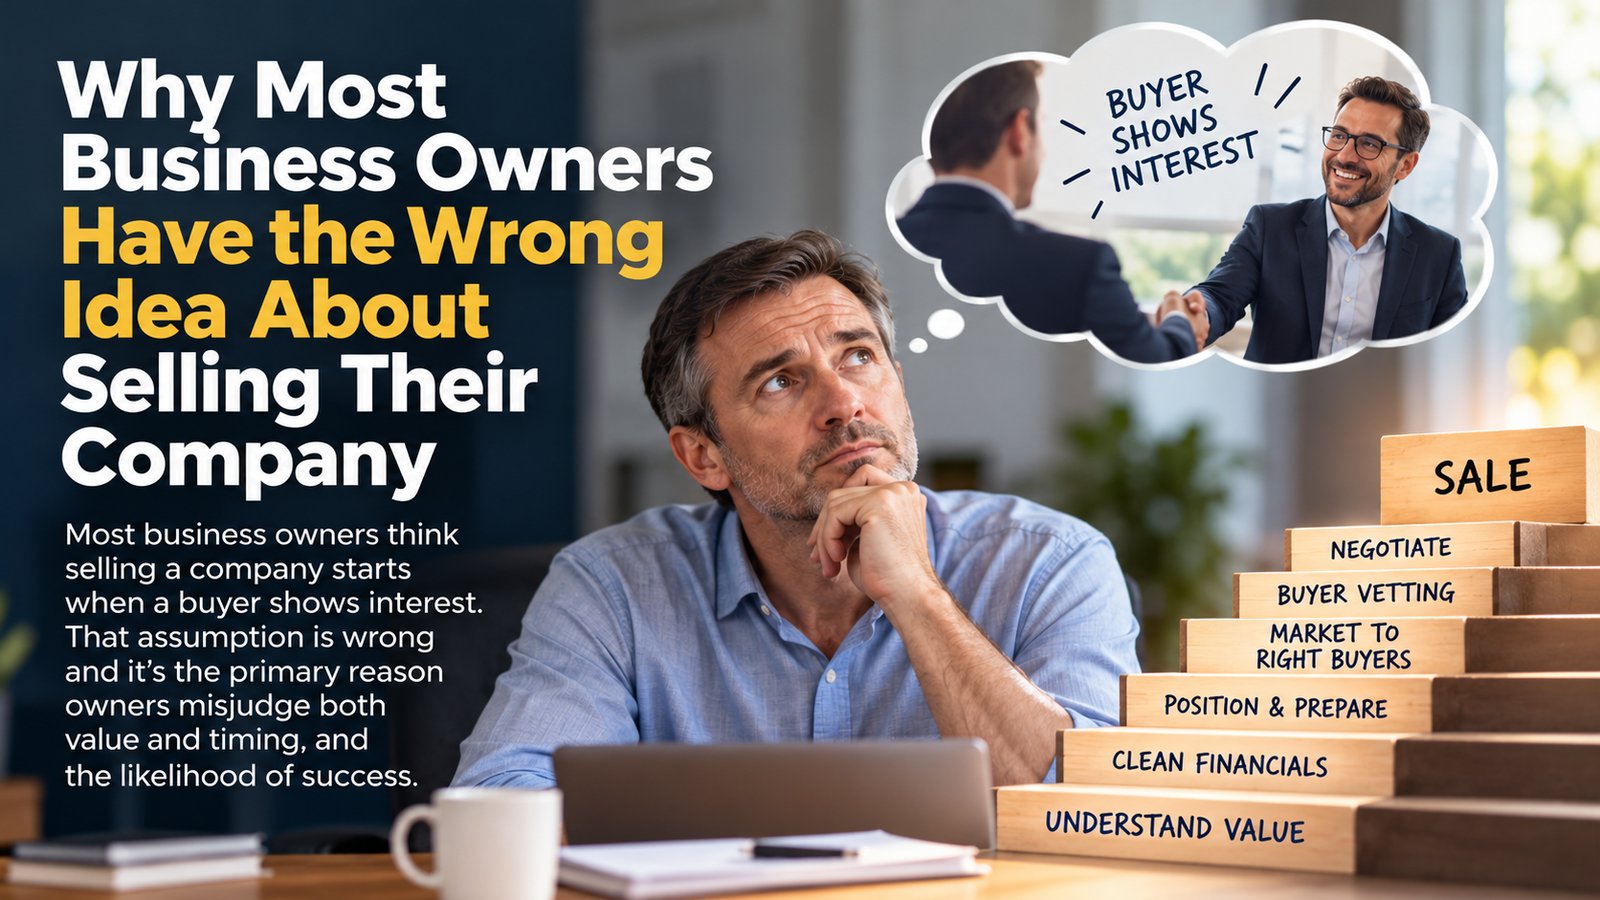
Most business owners think selling a company starts when a buyer shows interest.
That assumption is wrong and it’s the primary reason owners misjudge both value and timing, and the likelihood of success. Statistically more than 2 of 3 transactions fall apart during the process.
Selling a business is not something you do when you’re ready to exit. It’s something you prepare for long before you ever speak to a buyer.
The Core Misunderstanding
- Value is objectively determined
- Strong financials speak for themselves
- The deal will work itself out once talks begin
- Future potential will be obvious to a buyer
None of these are true.
Buyers don’t search for value — they discount risk. And the more uncertainty they see, the more aggressively they do it.
If the seller hasn’t already defined the narrative, controlled the process, and justified the valuation, the buyer will do it for them, in their own favor.
The Problem With “What a Buyer Could Do”
Many sellers focus heavily on arguing a potential upside:
- “A buyer could easily scale this”
- “With more sales/marketing effort, this could be much bigger.”
Those statements are not evidence.
Future potential only matters when it is:
- Credible
- Quantifiable
- Already supported by systems, data, or traction
Otherwise, it’s viewed as execution risk and risk reduces value. If growth depends on ideas rather than proof, buyers won’t price it in. They’ll discount it.
Why One Buyer Is Never Enough
When owners say, “I’m happy to talk if you have a buyer,” or when they engage with a single buyer informally, they’re unintentionally giving away leverage.
There is:
- No market validation
- No competitive tension
- No pressure on the buyer to act decisively
At that point, pricing becomes exploratory, not competitive, and the buyer controls the pace. That’s not a sale process. That’s a negotiation from a position of weakness.
Strong exits are the result of process discipline, not because a buyer is very interested.
Valuation Is a Defense, Not an Opinion
Valuation isn’t a range or a guess. It’s a justified position built on facts.
It must be supported by:
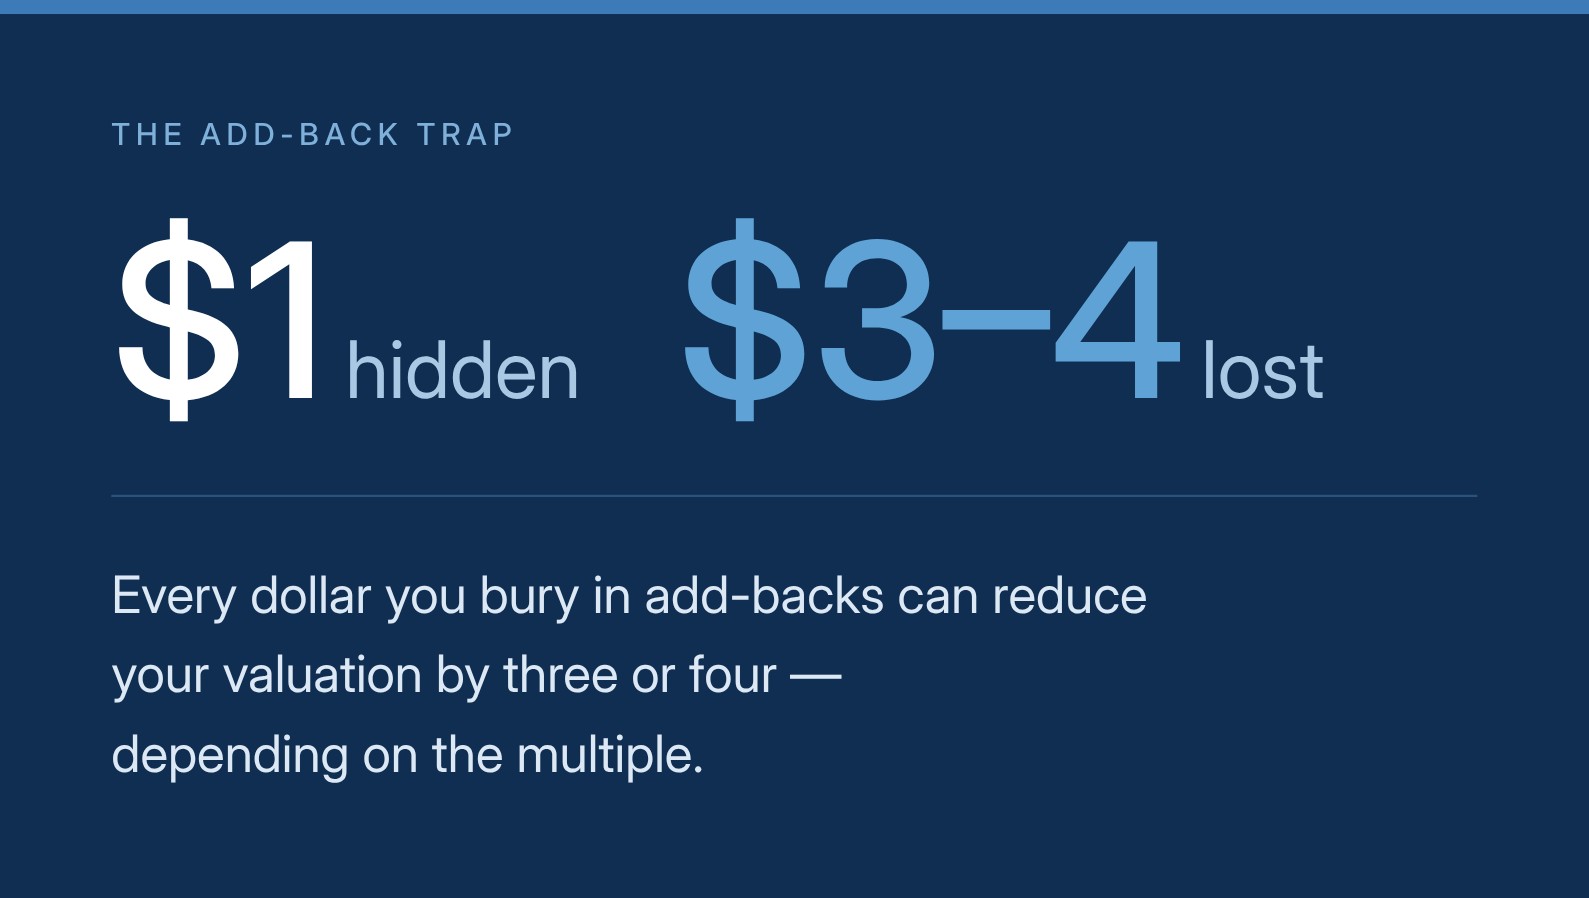
- Normalized and explainable earnings
- Reduced owner dependency
- Clear, documented drivers of performance
- Risks that have already been addressed — not explained away
When those elements are missing, buyers rarely argue. They simply adjust their number. Downward.
The Right Mental Model
Owners who get this right think differently — early.
They stop asking, “Who might buy this?”
And start asking, “How will a buyer objectively underwrite this business?”
That shift changes how decisions are made - sometimes years in advance - and it’s what creates optionality, leverage, and ultimately, value.
The best exits don’t happen because the timing was perfect.
They happen because the business was prepared to be sold and the owner pulled the trigger at the right time.
That’s how strong exits are engineered.
What are businesses in your industry selling for? Request a complimentary Industry Multiples Insight.